
Prospectus
A corporate treasury banking underwriting service for community development aid.
ABOUT
MADIBA369 is private organization/program underwriting that is parallel of 6 key factor of standard underwriting for Character, Capacity, Conditions, Collateral, Capital and Credit. MADIABA369 does not undewrite the State, parish, municipality, political subdivision, or a governmental authority issuing public debt.
OPERATING STATUS
Privately managed, member-funded community investment program serving a public/community development purpose.
MADIBA369 restricts governmental lending or pledging of public credit to private persons or enterprises except as authorized. CONST 7 14
No obligation of MADIBA369 or HSC constitutes an obligation of the State of Louisiana, any parish, municipality, political subdivision, governmental authority, or taxing jurisdiction, and no governmental taxing power, full faith and credit, or public credit is pledged to the payment of any MADIBA369 investment interest.
MADIBA369 does not offer state obligations or funding. Louisiana’s State Bond Commission authority is principally directed at obligations of the state and political subdivisions, with specific statutes extending approval requirements to certain public/quasi-public entities. Louisiana’s Constitution also specifically addresses bonds issued by political subdivisions. RS 39:1403
Residents
→ voluntarily become MADIBA members
→ contribute their own private funds
→ receive a contractual/securities investment interest
→ HSC privately administers MADIBA
→ projects/programs are privately managed
→ repayment/redemption comes from MADIBA’s investment assets/revenues
→ no parish/municipal taxing power or full faith and credit backs the obligation
| Characteristic | Government GO bond | Your proposed MADIBA |
|---|---|---|
| Issuer | Political subdivision | Private HSC/MADIBA structure |
| Investor | Public/private investors | Participating residents |
| Authorization | Governmental authorization | Private organizational/member agreements |
| Repayment | Government obligation | Contractual investment/program obligation |
| Taxing power | May be pledged | None |
| Full faith & credit | Government pledge | None |
| State Bond Commission | Potentially required | Potentially outside SBC jurisdiction |
| Securities law | Bond/securities law | Securities exemption + applicable state law |
| Banking settlement | Possible | Partner settlement bank |
| Audit/reporting | Government requirements | Private governance + securities/accounting requirements |
Louisiana’s Constitution expressly describes a general-obligation bond as an obligation backed by the political subdivision’s full faith and credit, with the governing authority responsible for levying sufficient ad valorem taxes.
HSC/MADIBA → private contractual obligation → member/investor capital → private assets/program revenues → no governmental guarantee → no governmental taxing authority,
VS
Parish → municipal bond → taxpayer revenues → full faith and credit → governmental debt.
MADIBA ARCHITECTURE
| Layer | Function |
|---|---|
| 1. MADIBA369 Governance & Underwriting Framework | Master rules governing membership, governance, underwriting, investment administration, project approval, risk controls, records, and resolution |
| 2. MADIBA369 Community | Board, community governance, membership representation, approvals, oversight, and policy authority |
| 3. Treasury Bank Data Center | Value Storage, Transfer & Investment Record functioning as the MADIBA369 treasury/recordkeeping system; maintains transaction, obligation, ownership, allocation, distribution, and reconciliation records |
| 4. Community Investment Program | Individual community investment project/program and issuer of the applicable securities or investment interests |
| 5. Investor/Member Ownership Register | Records each investor/member’s subscription, ownership/beneficial interest, transfers, distributions, and applicable restrictions |
| 6. Interstate Compliance | Rule 147 / 147A offering structure for qualifying intrastate offerings |
| 7. Outer State Compliance | Regulation D Rule 504 / Rule 506 structure for qualifying offerings involving out-of-state investors |
| 8. HSC Administrator / Underwriter / TPSP | Contractual administration, underwriting, treasury/payment processing, compliance controls, documentation, authorization, reconciliation, and TPSP functions |
| 9. Bank Regulated Settlement Layer | Master Escrow Account MEA, ODFI/payment-rail, settlement, posting, regulated banking, monitoring, and reconciliation functions |
| 10. Distribution / ROI / Dividend / Return-of-Capital Policy | Defines how realized value is classified and distributed according to the governing security or contractual interest |
| 11. Accounting & Tax Reporting Policy | Establishes transaction classification, books and records, investor reporting, tax reporting, and applicable federal/state treatment |
The operating flow
                 MADIBA GOVERNANCE
                  MADIBA COMMUNITY
                 Board & Oversight
                        │
                        ▼
          MADIBA GOVERNANCE & UNDERWRITING
                    FRAMEWORK
                        │
          ┌─────────────┴─────────────┐
          ▼                           ▼
 TREASURY BANK DATA CENTER         COMMUNITY
 Value Storage / Transfer       INVESTMENT PROGRAM
 Investment Record              Securities Issuer
          │                           │
          │                           ▼
          │                 Securities / Interests
          │                           │
          ▼                           ▼
 INVESTOR / MEMBER ───────► OWNERSHIP REGISTER
          │
          │
    ┌─────┴───────────────┐
    ▼                     ▼
LOCAL OFFERING       INTERSTATE OFFERING
147 / 147A           Reg D 504 / 506
    │                     │
    └──────────┬──────────┘
               ▼
        HSC ADMINISTRATOR
          UNDERWRITER
             TPSP
               │
               ▼
       BANK SETTLEMENT LAYER
               │
               ▼
      Regulated Payment /
      Settlement / Posting
               │
               ▼
        RECONCILIATION
               │
               ▼
   DISTRIBUTION / ROI / DIVIDEND
      / RETURN OF CAPITAL
               │
               ▼
       ACCOUNTING & TAX
          REPORTING
INVESTING FRAMEWORK
MADIBA369 Community Investment Platform is an issuer-administered investment and transfer platform through which eligible residents may subscribe for, hold, transfer, redeem, or otherwise dispose of qualifying MADIBA369 investment interests subject to applicable federal and state securities laws, offering restrictions, transfer restrictions, and HSC’s governing investment documents.
Resident Investor
↓
MADIBA369 Community Investment Platform
↓
Community Investment Ledger
↓
MADIBA Community Investment Interest
↓
Settlement Bank / Custody Account
↓
Cash settlement / redemption / permitted transfer
There are two ways for a resident to acquire Community investment value:
- Cash Escrow
- Resident contributes $10,000, for example.
- Settlement bank receives the money.
- HSC/TBO records the corresponding investment position.
- Investor receives the applicable MADIBA investment interest.
- HSC-funded investment / margin-type financing
- HSC provides financing or credit against an eligible investment transaction.
- The investor acquires community investment interest using the permitted financing structure.
- The obligation to HSC is separately recorded.
- Settlement still occurs through the bank.
Under Rule 147, for example, the SEC says securities purchased under the exemption are subject to a six-month limitation on resale to persons residing within the state. The resale itself also needs an applicable exemption from registration
Rule 147 Issue
For a Louisiana-focused MADIBA369 community model, the architecture could look like:
Louisiana resident
→ MADIBA offering
→ HSC/MADIBA issuer
→ HSC/Treasury Bank ledger
→ Louisiana-qualified investment interest
The Rule 147 framework requires the issuer to be organized in the state, have its principal place of business there, satisfy one of the specified in-state business tests, and limit offers and sales to in-state residents. Purchasers must also provide written residency representations.
This gives you a particularly interesting model for the North Louisiana community investment concept you’ve been developing.
But the six-month resale restriction means your platform needs a restricted-transfer period.
For example:
| Investor status | Platform action |
|---|---|
| New Louisiana investor | Eligible to subscribe |
| Cash investor | Investment position created |
| HSC-financed investor | Financing + investment position recorded |
| <6 months from issuer sale | Transfer restricted |
| ≥6 months | Transfer potentially permitted, subject to applicable exemption |
| Louisiana resident buyer | Potential eligible transferee |
| Out-of-state buyer | Blocked under Rule 147 |
| Redemption by MADIBA | Must comply with offering documents and securities law |
Rule 504 Issue
Louisiana regional/community expansion concept.
This means MADIBA could potentially be structured as a regional offering rather than strictly Louisiana-only.
Under Rule 504 MADIBA issuers can offer and sell up to $10 million of securities during a 12-month period, subject to the rule’s requirements and applicable state securities laws. A Form D is required within 15 days after the first sale.
Note: Rule 504 does not itself create a secondary trading market.
The SEC specifically cautions that securities issued under Rule 504 will generally be restricted unless additional requirements are satisfied, and resale restrictions can materially affect liquidity.
Therefore, the platform needs to distinguish:
Primary issuance
Investor → MADIBA/HSC → investment interest
from
Secondary transfer
Existing Investor → Eligible Buyer → permitted transfer
and
Redemption
Investor → MADIBA/HSC → cash settlement
Investing
“cash out when they sell” concept
Investor Enters
$25,000 cash
↓
MADIBA investment interest
↓
TBP records:
Investor Position = $25,000
Investor later exits
Suppose permitted sale/redemption value is: $31,000
↓
MADIBA/TBO calculates:
Gross proceeds = $31,000
↓
less applicable:
- financing balance
- fees
- taxes/withholding where applicable
- contractual deductions
↓
Net settlement
↓
Settlement bank
↓
Investor’s external bank account.
369 AUTHORITY
369 Authority is autonomous designed governance that foster independent economic growth, underwriting guarantee, research, and development programs under a commercial law. This enables community and entities to pursue shared objectives across financial, cultural, social, and professional sectors through structured contracting.
Administrative Duty
Executive Power
- Implement programs
- Managing program
- Carrying out legistrative decisions.
Board Duty
Legislative Powers
- Stakeholders
- Establishing Policies
- Managing Budgets
- Authorizing Documents.
- Managing Meeting
- Committee Oversight
Amend & Resolution
Judicial Powers
- Agreement
- Jurisdiction
- Arbitration
- Notice
- Conference
- Meeting
- Hearing
- Resolution
- Enforcement
MEMBERSHIP
Building private public partnerships between your business, investors, banks and sponsorship for related research and development programs with the following:
- Profile
- Agreement
- Subscription Investment
- Certification
- Creating Association
- Online Meeting Structure
- Authority Governance and Functions
- Operational Policies and Procedures
Eligibility
- Who participates
- Which community project qualifies
- How the project is structured
- What capital is committed (Match Ratio)
- What investment/financing arrangement applies
- What contractors and merchants are authorized
- What benefits or returns are allocated
- What conditions must be satisfied before funding
- How project performance is monitored
- How the investment is audited and reported
VIRTUAL CARD
Members way to receive Credit and Cash Distribution through regulated banking infrastructure
Credit Card
Designed for cash credit member
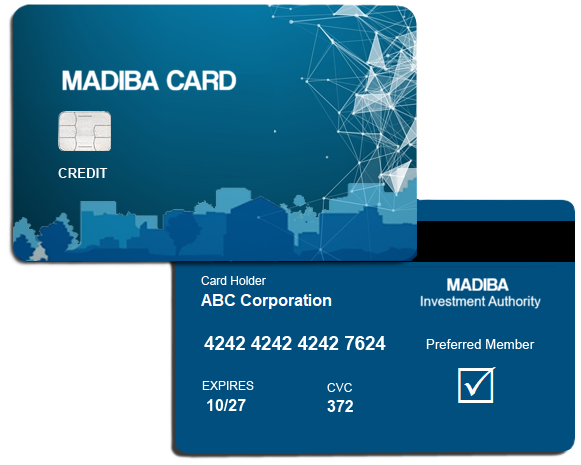
This card is for Guarantor’s or Fiduciary assigned General Contractors Expenses as credit distributed through MADIBA .
Debit Card
Designed for cash flow members
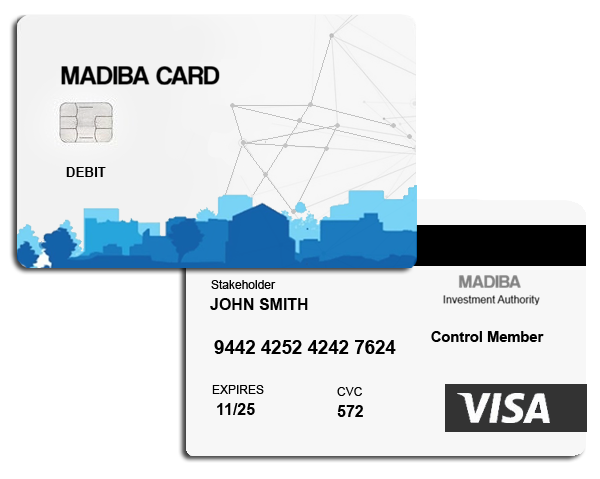
This card is for Beneficiary Members investor who receive procurement and cash benefits through MADIBA.

CLEARING & SETTLEMENT
MADIBA transactions handled through HSC Treasury to Bank (T2B) system integration with regulated banking infrastructure.

REVENUE PROJECTIONS
A hypothetical Year 3 operating model.
Assume:
Technology
25 enterprise customers × $60,000 = $1,500,000
Guarantor Member Subscriptions
50 organizations × average $30,000 = $1,500,000
Beneficiary Contribution
$250M administered × 0.25% = $625,000
Underwriting
$150M annual funded volume × 1% = $1,500,000
Investment management
$100M AUM × 1% = $1,000,000
Project administration
$100M project capital × 0.50% = $500,000
Servicing
$100M project capital × 0.50% = $500,000
Data/reporting
50 customers × $750/month = $450,000
Integration
15 implementations × $40,000 = $600,000
Professional services
3,000 hours × $225 = $675,000
Investment income
Illustrative: = $250,000
Illustrative Year-3 Revenue
| Revenue Source | Year-3 Revenue |
|---|---|
| Technology licensing | $1,500,000 |
| Platform subscriptions | $1,500,000 |
| Treasury administration | $625,000 |
| Underwriting | $1,500,000 |
| Investment management | $1,000,000 |
| Project administration | $500,000 |
| Servicing | $375,000 |
| Data/reporting | $450,000 |
| Integration | $600,000 |
| Professional services | $675,000 |
| Investment income | $250,000 |
| Total | $8,975,000 |
So an illustrative mature Year-3 model could generate approximately $9.0 million in gross revenue.
The important point is that only about $250,000 of that example comes from investment income. The business is primarily supported by technology, administration, underwriting, management and services.
Three-Stage Revenue Forecast
These are planning assumptions, not forecasts of guaranteed results.
| Year 1 | Year 2 | Year 3 | |
|---|---|---|---|
| Technology licensing | $250K | $750K | $1.50M |
| Subscriptions | $300K | $800K | $1.50M |
| Treasury administration | $100K | $300K | $625K |
| Underwriting | $250K | $750K | $1.50M |
| Investment management | $100K | $500K | $1.00M |
| Project administration | $100K | $300K | $500K |
| Servicing | $50K | $175K | $375K |
| Data/reporting | $100K | $250K | $450K |
| Integration | $200K | $400K | $600K |
| Professional services | $300K | $500K | $675K |
| Investment income | $50K | $125K | $250K |
| Total Revenue | $1.70M | $4.85M | $8.975M |
The More Important Metric: Revenue Per Institutional Customer
I would make this a major part of the investor story.
A large institutional customer could potentially generate:
$60,000 – technology license
$30,000 – platform subscription
$25,000 – treasury administration
$50,000 – underwriting
$25,000 -data/reporting
$40,000 – integration
= $230,000+ first-year customer revenue
Then recurring revenue could potentially become:
$100,000–$150,000+ annually
Depending on assets, transactions and services.
That creates a much more compelling economic model than simply selling $500/month software.
Long-term Projections
HSC is targeting the following approximate mix over time:
Technology / SaaS – 30%
Underwriting & transaction services – 25%
Treasury administration – 20%
Investment/project administration – 15%
Professional & integration services – 7%
investment/other income – 3%
This creates a model where recurring technology and administration revenue forms the foundation while transaction volume and investment activity provide upside. It also avoids making investment gains the primary justification for the business valuation.